PORT ALBERNI | VANCOUVER ISLAND | VIRTUAL ACROSS BC

Your Vancouver Island mortgage broker,  since 2009.

2009

Helping clients since

5.0  ★★★★★

120+ Five Star Google Reviews

ALL OF B.C

Fully virtual, wherever you live

Port Alberni Parksville Qualicum Beach Nanaimo Ladysmith Duncan Courtenay Comox Campbell River Tofino Ucluelet Victoria Virtual across BC

Why work with me

The care and knowledge of a

professional broker, start to finish.
01

One relationship

A personal experience, start to finish

You work directly with me, not a team member or a call centre. I take the time to understand your goals, answer every question, and make sure you always know what comes next.

02

Education first

Advice you can actually understand

The best mortgage decisions are informed ones. I explain everything in plain language, without jargon or pressure, so you always know the reason behind every recommendation.

03

Since 2009

Experience and advocacy at every stage

From first homes to refinances, renewals, self-employed files and separations, I take a solution-focused approach and advocate for you every step of the way.

RABINDER DHILLON

MORTGAGE BROKER

Thank you for taking the time to visit my website. I look forward to working with you!

Since 2009, I have dedicated my career to helping people make informed decisions about their mortgage options. Taking on a mortgage is one of the largest financial commitments most individuals will make in their lifetime.


My goal is to ensure every client understands that I work for them—that their goals, concerns, and needs are all equally important. I strive to build long-term relationships based on trust, transparency, and understanding. My priority is to help clients fully explore their options so they can make confident, well-informed choices that support their long-term financial success.


I take pride in being a single point of contact for my clients, offering the personal attention and expertise they deserve throughout the entire mortgage process—and beyond. Mortgages can be complex and, at times, overwhelming. By liaising directly with lenders on my clients’ behalf, I ensure they are informed, comfortable, and never lost in lender jargon. With patience, persistence, and creative problem-solving, I work diligently to find solutions for even the most challenging files. There is always a path forward—sometimes a solution, sometimes a plan toward one.


One of the experiences I am most fond of was my time in the Alberni Valley promoting financial literacy among teens. From 2012 until the onset of COVID-19, I volunteered as a guest lecturer at ADSS, teaching students about the value of money—from saving and understanding credit to investing for the future. It was incredibly rewarding to see their curiosity grow and to know I was helping them build a foundation of financial confidence. I still believe that knowledge is power, and that the more young people understand about money, the stronger and more secure their futures can be.

Rooted on the Island, working across BC

Local to Vancouver Island.

Available anywhere in BC.

Port Alberni is one of Vancouver Island's most affordable markets, which makes it a real opportunity for first-time buyers priced out of Victoria or Nanaimo, and for investors looking Island-wide. Knowing the local market is part of how I help.


And because my process is fully virtual, you do not need to be nearby to work with me. From Tofino to Victoria to the Lower Mainland, I help clients across the province through phone, video and secure digital tools, with the same personal service either way.
LET'S CONNECT

Kind words from clients

Trusted by hundreds for all their mortgage needs

Rabinder has been amazing to deal with, she walked us through everything step by step and made the entire process seem effortless. She was nothing but kind and has a very easy going demeanour that makes you feel like you are talking with an old friend rather than dealing with finances. I would highly recommend her to anyone and look forward to working with her again in the future. Thank you Rabinder for making us feel confident in our choice to work with you!

Brandy Watson

Working with Rabinder for our home purchase has been nothing short of a dream! She is knowledgeable, efficient and so helpful. She walked us through all our options and helped us decide which product would be best for our situation. Rabinder provided updates throughout the process which allowed us peace of mind through every step. Thanks again, Rabinder!

Amanda Stephens

I wish I would have called her sooner. My first contact with her was so positive, she could fix our financial situation, I was actually thinking "is this possible" it was and she did. I had some challenges along the way, but, she helped me with all of it. We were with a private lender and getting no where and I felt stuck due to my disability and my mom's OA. We are now way more financially stable, working down our mortgage and can sleep better at night. The struggle is over. I asked if we would ever meet her and she came to our home to sign papers. She was just lovely. Knowledgeable, professional, and very friendly, with a smile that lites up the room. Thank you Rabinder!

Diana Wissman

MORTGAGE SERVICES

What I can help you with

Whether you are buying your first home or your fifth, navigating a major life transition, or ready to put your home's equity to work — there is a mortgage strategy built for where you are right now.

First-Time Home Buyers

First-Time Home Buyers

No jargon and no pressure. Just clear, patient guidance through every step of buying your first home, so the whole thing feels a lot less overwhelming.

Home Purchase

Home Purchase

Moving up, relocating, or buying your next place? I compare lenders across the market to find the mortgage that fits your life, not just the lowest rate.

Refinance

Refinance

Access your equity, fund a renovation, or improve your cash flow. I explain every option plainly, and I will tell you honestly if refinancing is not the right move.

Mortgage Renewal

Mortgage Renewal

Your renewal is a chance to do better, not just to sign. I compare the whole market and review your goals before you commit to another term.

Separation & Divorce

Separation & Divorce

Keeping the home, spousal buyouts, qualifying on one income. I handle these with care and discretion, at whatever stage you are in, and never any pressure.

Self-Employed

Self-Employed

Self-employed does not mean unqualified. It means your application needs to be built the right way, and I know how to present your income to lenders.

New to Canada

New to Canada

New to the country and buying your first home here? There are lender programs built for newcomers, even if your Canadian credit is still building. I will explain every step in plain language, with no pressure.

Reverse Mortgage

Reverse Mortgage

You have spent years building equity in your home. A reverse mortgage can let homeowners 55 and older access it, tax-free and with no monthly payments, without selling. I will give you an honest look at whether it fits.

Separation & Divorce

Separation & Divorce

A separation raises hard questions about the home. Can you keep it? Can you buy out your partner? I handle these with care and discretion, and help you understand your options at whatever stage you are in.

My Mortgage Tools

Download my free mortgage app
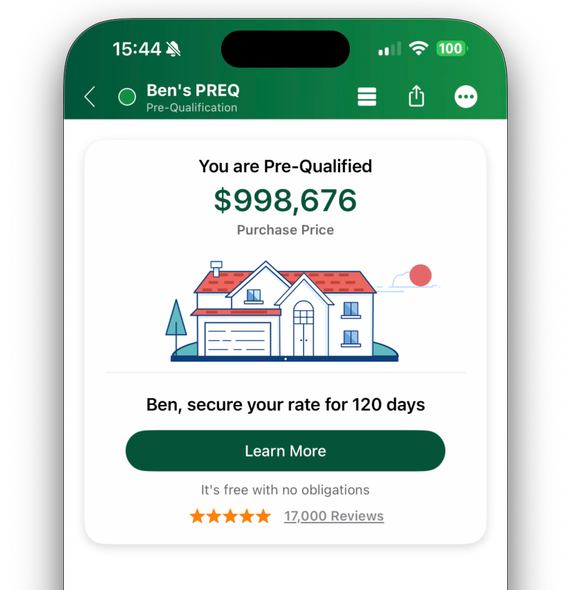
Here's What You Can Do ⤵ 

  • Calculate your total cost of owning a home
  • Estimate the minimum down payment you need
  • Calculate Land transfer taxes and the available rebates
  • Calculate the maximum loan you can borrow
  • Stress test your mortgage
  • Estimate your Closing costs
  • Compare your options side by side
  • Search for the best mortgage rates
  • Email Summary reports (PDF)
  • Use my app in English, French, Spanish, Hindi, and Chinese
Let's Run Some Numbers

CALCULATE

Whether you're just getting started, have a home in mind, or want to refinance or renew an existing mortgage, why not start by using my online calculator? 

CALCULATE

APPLY NOW

You've run some preliminary calculations, you've signed the consent form, the next step is to go through my online mortgage application.  
APPLY

 Common questions

The questions I hear most

  • How much mortgage can I qualify for?

    It depends on your income, your existing debts, your down payment and your credit, all measured against the lender's limits and the mortgage stress test. Most buyers qualify for roughly four to five times their household income, but the real number is personal. I will review your full picture and give you a clear, honest amount to shop with, rather than a rough guess from an online calculator.

  • How much down payment do I need to buy a home in BC?

    The minimum in Canada is 5 percent on the first 500,000 dollars of the price and 10 percent on any portion between 500,000 and one million. With less than 20 percent down, your mortgage is insured, which is completely normal and gives you access to the best rates. First-time buyers in BC may also qualify for a Property Transfer Tax exemption, which I will help you understand.

  • What is the difference between a pre-qualification and a pre-approval?

    A pre-qualification is a quick estimate based on an online calculator, with nothing verified. 


    A pre-approval is stronger. I review your documents and credit and confirm your range with a lender, and it comes with a rate hold that protects you if rates rise. When you make an offer, a real pre-approval carries far more weight.

  • Can I get a mortgage if I am self-employed?

    Yes. Being self-employed just means your income needs to be presented the way lenders want to see it. If your taxable income is lower than what you actually earn, there are lenders and programs built for exactly that. I will explain what documents you need and match you to a lender who understands self-employed income.

  • Should I renew with my current lender, or shop around?

    Rarely should you simply sign your lender's first renewal offer. It is usually not their best rate, and your renewal is a chance to review whether your mortgage still fits your life. I compare multiple lenders, factor in your goals and any life changes, and explain penalties and prepayment options in plain language so you can decide with confidence.

  • Can I keep my home after a separation or divorce?

    In many cases, yes. A spousal buyout lets one partner refinance to buy out the other's share, and under a special program it can be treated like a purchase, allowing you to borrow more of the home's value than a standard refinance. Support payments can sometimes be used as income too. I handle these files with care and discretion, and I will walk you through your options without pressure.

  • How quickly can I get pre-approved?

    In most cases we move quickly once we have your documents — many pre-approvals are completed within 24–48 hours. Having your income documents, employment confirmation, and financial statements ready ahead of time speeds things up considerably.

  • Do I have to live in Port Alberni to work with you?

    Not at all. Port Alberni is my home base, but my process is fully virtual and has been for years. I work with clients across Vancouver Island and all of British Columbia through phone, video calls, secure document uploads and electronic signatures, so you can complete your mortgage from anywhere in the province.

Still have a question?

CONTACT

I provide mortgage services to loyal clients in a transparent environment, with an authentic voice, helping them feel protected, and save time and money.

LET'S CONNECT

VALUED RELATIONSHIPS


I've developed excellent relationships with Lenders, Realtors, Appraisers, Solicitors & Notaries, Home Inspectors, and many other service providers. 
MORTGAGE RESOURCES
By Rabinder Dhillon September 16, 2026
Buying a home is one of the biggest financial commitments you’ll ever make. That’s why lenders want to be sure you can handle your mortgage payments—not just today, but also if interest rates rise in the future. This is where the mortgage stress test comes in. Many Canadians hear the term but aren’t entirely sure what it means or how it affects them. Let’s break it down in plain language. What Is the Mortgage Stress Test? The stress test is a rule introduced by the federal government that requires all mortgage applicants to qualify at a higher rate than the one they’ll actually pay. Currently, you must qualify at the greater of your contract rate + 2% or the benchmark qualifying rate (set by the Office of the Superintendent of Financial Institutions). For example: If your lender offers you a 5-year fixed mortgage at 5.25%, you must show you could still afford the payments at 7.25% . Even if rates don’t rise that high, the stress test ensures you won’t be overextended if they do. Why Does It Matter? The stress test protects both borrowers and lenders by: Preventing over-borrowing : It ensures you don’t take on more debt than you can realistically handle. Preparing for rate hikes : With interest rates fluctuating, it’s a safeguard against sudden increases. Strengthening financial stability : It lowers the risk of defaults, protecting the housing market as a whole. While it can sometimes feel like a barrier—reducing the amount you qualify for—it’s ultimately designed to keep you from becoming “house poor.” How Does It Impact Buyers? The stress test can significantly affect your homebuying budget. For example, without it, you might qualify for a $600,000 mortgage, but with the stress test applied, you may only qualify for $500,000. That doesn’t mean your dream of homeownership is out of reach—it just means you may need to adjust expectations or explore other strategies, such as: Increasing your down payment Paying down existing debts Considering alternative lenders who may have different qualification standards Why Work With a Mortgage Professional? Every lender applies the stress test, but not every lender views your application the same way. An independent mortgage professional can: Shop multiple lenders to find the best fit Run affordability scenarios at different rates Help you understand how much house you can truly afford—without stretching your finances too thin The Bottom Line The mortgage stress test isn’t meant to stop you from buying a home—it’s there to protect you from financial strain down the road. By understanding how it works and planning ahead, you can make smarter choices and buy with confidence. If you’re thinking about purchasing a home, refinancing, or simply want to know how the stress test affects your options, connect with us today. We’ll help you stress-test your budget and find the mortgage solution that works best for you.
By Rabinder Dhillon September 9, 2026
You’ve found the right home, your offer’s been accepted, and your financing is approved—congratulations! But before you can pick up the keys and celebrate, there’s one more important stage: the closing process. Closing is the final step in your homebuying journey, where all the paperwork, legal details, and financial transactions come together. It can feel overwhelming if you don’t know what to expect, but with the right preparation, closing can be smooth and stress-free. Here’s a step-by-step guide to help you understand the process. Step 1: Hire a Lawyer or Notary A real estate lawyer (or notary, depending on your province) handles the legal side of closing. They will: Review the purchase agreement and mortgage documents Conduct a title search to confirm the seller has the legal right to sell the property Ensure the mortgage lender is properly registered on the title Handle the transfer of funds between you, the lender, and the seller Your lawyer or notary will be your main point of contact during closing, so choose one you trust and who communicates clearly. Step 2: Finalize Your Mortgage Your lender will send the mortgage instructions directly to your lawyer or notary. At this stage: You’ll provide proof of property insurance (lenders require this before releasing funds) You’ll confirm your down payment and closing costs are available in your lawyer’s trust account The lawyer will prepare all documents for your review and signature Step 3: Pay Closing Costs Closing costs typically range from 1.5% to 4% of the purchase price. These can include: Legal fees Title insurance Land transfer tax (where applicable) Adjustments for property taxes or utilities prepaid by the seller Home inspection or appraisal fees (if not already paid) Your lawyer will provide a final statement of adjustments so you know exactly how much is due on closing day. Step 4: Sign the Paperwork A few days before closing, you’ll meet with your lawyer or notary to sign all the necessary documents, including: Mortgage agreement Title transfer Insurance confirmations Statement of adjustments Bring valid government-issued ID to this appointment. Step 5: Transfer of Funds On the day of closing: Your lender sends the mortgage funds to your lawyer Your lawyer combines these funds with your down payment and pays the seller Legal ownership of the property is transferred into your name The lender is registered on title as a secured creditor Step 6: Get the Keys! Once the paperwork is filed and the funds have cleared, your lawyer will confirm that the transaction is complete. You’ll then get the keys to your new home—officially making it yours. The Bottom Line The closing process is a series of important steps, but with the right team in place, it doesn’t have to be stressful. By working closely with your mortgage professional and lawyer, you’ll have guidance every step of the way—from signing the documents to turning the key in the front door. If you’d like help preparing for the closing process—or want a clear breakdown of your own closing costs— connect with us today.
By Rabinder Dhillon August 26, 2026
Why the Property Matters When You’re Qualifying for a Mortgage When qualifying for a mortgage, lenders typically look at four core areas: Income Credit Down payment or equity The property itself Most buyers focus heavily on income, credit, and savings—and for good reason. But even if those boxes are checked, the property can still determine whether a mortgage is approved. Why Lenders Care About the Property From a lender’s perspective, the property is the collateral for the mortgage. In the unlikely event of default, they need to know the home can be sold quickly and at fair market value to recover their funds. Because of this, lenders are careful about the condition, value, and marketability of any property they finance. Homes that are in poor repair, unconventional, or overpriced can raise red flags—even when the borrower is well qualified. Appraisals Are Always Part of the Process Every mortgage requires an appraisal to confirm value. Insured mortgages (through CMHC, Sagen, or Canada Guaranty) often use an automated valuation model completed online. Conventional mortgages typically require a full, on-site appraisal by a certified appraiser. This appraisal is not optional and happens after an offer is accepted—not at the pre-approval stage. Why Pre-Approvals Aren’t a Guarantee A pre-approval is a great first step, but it only assesses you, not the property. Once you’ve made an offer, the lender must approve the specific home you’re buying. Understanding this upfront helps avoid surprises and confusion later in the process. The Risk of Buying Without a Financing Condition In competitive markets, buyers sometimes remove financing conditions to strengthen their offer. However, this comes with risk. If the appraisal comes back low—or the lender is concerned about the property’s condition—you could be denied financing after the offer is firm. In that scenario, your deposit may be at risk. Buying a Home That Needs Work If you’re considering a property that isn’t in perfect condition, there are solutions. A purchase plus improvements program allows you to buy a home and include renovation costs in your mortgage. The process is structured and requires planning, but it can be an excellent way to turn a fixer-upper into a great long-term investment. Final Thoughts Mortgage approval isn’t based solely on your finances—the property matters just as much. Knowing this ahead of time helps you make smarter offers, reduce risk, and plan more effectively. If you’re buying a property that needs work or want clarity on how a lender may view a specific home, feel free to reach out. I’d be happy to walk you through your options and help you plan with confidence.
Show More